Nov 11, 2008

FHFA Modification Program Details

Here is the press release from the FHFA. Note that this does not include principal reduction as a solution to create an affordable payment, and is limited to: "extending the term, reducing the interest rate, and forbearing interest".

This is intended to help "thousands" (a drop in the bucket unless it is several hundred thousand), and seems to encourage homeowners to stop making payments until they are 90 days late.

Here are some excerpts:

Q: What is a streamlined modification?

A: A streamlined modification is a modification that requires less documentation and less processing. In this case, the streamlined modification seeks to create a monthly mortgage payment that is sustainable for troubled borrowers by targeting a benchmark ratio of housing payment to monthly gross household income.

Q: What is the benchmark ratio?

A: This is the first time the industry has agreed on an industry standard. The benchmark ratio for calculating the affordable payment is 38 percent of monthly gross household income. Once the affordable payment is determined, there are several steps the servicer can take to create that payment – extending the term, reducing the interest rate, and forbearing interest. In the event that the affordable payment is still beyond the borrower’s means, the borrower’s situation will be reviewed on a case-by-case basis using a cash flow budget.

Q: Why is it necessary?

A: With the rise in serious delinquencies and increasing number of loans in foreclosure, this program will help borrowers who have missed three or more payments, but want to keep their homes. Because the eligibility requirements and process are streamlined and consistent, the program will allow servicers to reach more borrowers more quickly.

Q: Who is eligible?

A: The highest risk borrower, who has missed three payments or more, owns and occupies the property as a primary residence, and has not filed bankruptcy. The loan is a Freddie Mac, Fannie Mae or portfolio loan with participating investors. To qualify for the streamlined modification, the borrower must certify that he or she experienced a hardship or change in financial circumstances, and did not purposely default to obtain a modification.

Q: Why must the borrower be 90 days delinquent? Why not earlier in the delinquency cycle?

A: This is a streamlined solution targeted to reach the most at risk borrower. For borrowers who do not qualify, other solutions are available. This in no way substitutes for the meaningful efforts by all servicers and investors that are currently in place. The 212,000 workouts reported by HOPE NOIW in September are testimony to that fact. We will continue to see those efforts produce meaningful results.

Q: How many people will this help?

A: While difficult to assess, it is clear delinquencies are predicted to continue well into 2009. Foreclosure estimates are significant. Having a streamlined approach will assist many borrowers who default and more quickly. We estimate this will ultimately help thousands of borrowers.

Q: How do borrowers apply?

A: To be considered for the program, a seriously delinquent borrower should contact his or her servicer and provide the requested information – monthly gross household income, association dues and fees, and a hardship statement.

Q: How do borrowers complete the modification process?

A: Upon receiving the Modification Agreement from the servicer, the borrower signs it and returns it with the 1st payment at the modified terms along with income verification. Once the borrower makes three payments at the modified terms and the account is current as of day 90 of the modified plan, the modification is complete.

Q: When will servicers start offering this program?

A: We expect that by December 15th, servicers will be positioned to work with eligible borrowers.

source: calculated risk

link to the original post:
http://calculatedrisk.blogspot.com/2008/11/fhfa-modification-program-details.html

Fort Lauderdale Blog and Real Estate News
Rory Vanucchi
RoryVanucchi@gmail.com

www.LasOlasLifestyles.com
www.FortLauderdaleLiving.net


For Many, 20% Down Payment Is All That’s Left

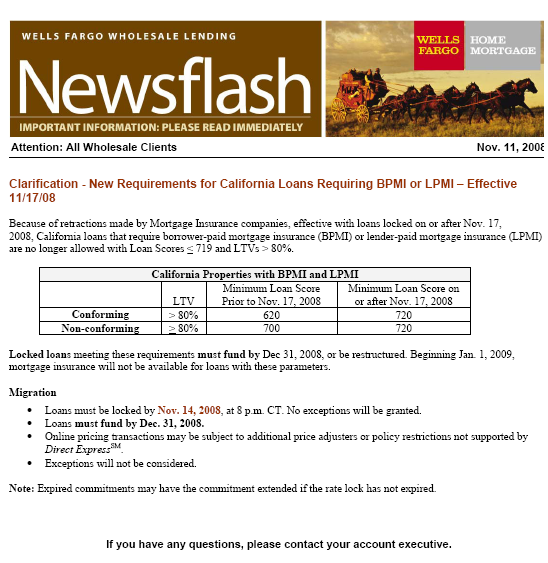
This announcement from Wells is the first I have seen but others should follow suit this week.

I have done numerous reports on the mortgage insurers and how it does not matter what Fannie and Freddie do with respect to loan-to-value, its all about what the mortgage insurers will do. See stories below for how we got here.


In CA (other states as well) due to mortgage insurer ‘challenges’, the MINIMUM credit score required to do any loan (Fannie/Freddie included) over 80% is now 720 from the previous 620. I am not sure the percentage of folks with over 720 scores vs. under but regardless, this will take a massive number of people out of the market.

Putting 20% down is a very rare thing especially in this housing market. Over 50% of all sales came from the foreclosure stock and move-up buyers are not driving force - it is first-time home buyers, renters and investors. While investors usually have to put down at least 20%, first-time buyers and renters can put down less through Fannie and Freddie. Until recently, in CA you could purchase a home with 5% down under 720 score.

Ultimately, this will be great for housing in the future, as home owners will be nowhere near as leveraged in their home. But between now and the years it takes to get to ‘ultimately’, you must be aware of how damaging things like this can be to housing. -Best, Mr Mortgage


source: mr mortgage
http://mrmortgage.ml-implode.com/2008/11/11/for-many-20-down-payment-is-all-thats-left/

Fort Lauderdale Blog and Real Estate News
Rory Vanucchi
RoryVanucchi@gmail.com

www.LasOlasLifestyles.com
www.FortLauderdaleLiving.net

Revised U.S. Sugar deal could be sweet for Florida Crystals


Mechanical problems with his plane forced Gov. Charlie Crist to scrap plans to come to South Florida, where he was to announce a scaled-down version of the state’s deal with U.S. Sugar Corp.

However, the revised deal was outlined in a press release issued by U.S. Sugar. It indicates that the state will now purchase 181,000 acres from U.S. Sugar, instead of the original 187,000 acres, for $1.34 billion. The original price tag was $1.75 billion. The new deal includes a leaseback of land for $50 an acre until 2016.

U.S. Sugar will not be selling its mill, refinery, citrus processing facilities, railroads, office building and equipment to the state, according to the press release.

“After months of negotiations, it became clear that the best transaction was for the state to buy the land and for U.S. Sugar to keep the assets,” said Robert Coker, U.S. Sugar’s senior vice president of public affairs. "This is a good deal for the state, U.S. Sugar and our shareholders."

The new deal will allow the South Florida Water Management District to purchase all of the land needed to move forward with the restoration of the Everglades, Coker noted. And it can be done at a cost less than originally anticipated. In addition, he said, the company "will be able to continue farming to ensure that jobs are safeguarded for the next seven years."

The deal was revised because "the financial and real estate world has changed" since it was announced in June, according to a fact sheet issued by U.S. Sugar.

"It made more sense financially for both parties to carefully consider terms that would be fair to both sides — for the state to purchase land for environmental restoration and for U.S. Sugar to keep its industrial assets," it stated.

The buyout plan has been evolving during negotiations among the governor’s office, U.S. Sugar, the water management district and the Everglades Coalition of environmental groups.

Everglades Foundation CEO Kirk Fordham applauded the downsizing of the buyout expenses.

“I think it’s the same great deal for the people of Florida at a lower cost," he said. "The goal was not to own the facilities, but to get the land so you can store and move the water to the Everglades."

Matt Schwartz, of the Sierra Club's Broward County group, said he was surprised the state hasn’t tried to include Palm Beach County in the negotiations. The county has recently been moving ahead with land use permissions for rock mining in the sugar-growing areas.

One of the biggest issues in the buyout plan is what will become of U.S. Sugar’s new processing mill in Clewiston, which is in the proposed buyout area.

Gaston Cantens, Florida Crystals vice president for corporate relations, said his company might be interested in purchasing the mill.

“We’re certainly open-minded about this,” he said. “The caveat we’ve always had is how much land will you have to grow sugar cane to put into the Clewiston mill? If you have no sugar cane, what will you do with the mill?”

In an interview Tuesday afternoon, Cantens said Florida Crystals could be interested in owning the mill if there was sugar production around it.

“Would we be interested in the mill? Absolutely,” he said. “But, it would depend on how much land and sugar is available. Our mill in Okeelanta is state of the art. It’s not brand new, but it has been updated and upgraded, and it’s basically computerized. We have no interest in scrapping Okeelanta, where we have a processing plant, distribution center and power plant.”

Florida Crystals and U.S. Sugar share the cane fields of Central Florida almost equally. Any plan to buy out U.S. Sugar to create a flow-way for Everglades waterways would have a big impact on Florida Crystals, and could require its cooperation.

Sugar grower Ardis Hammock of Clewiston, who came to hear the governor speak, was disappointed Crist didn't show – and even more disappointed he hasn't visited Clewiston since announcing the sugar buyout plan. She said she might sell out her land for the right money, but she is not happy about the government buyout in general.

"I feel very much in limbo," Hammock said. "A mill can't stay viable for long without land to support it."

Crist, whose plane was forced to make an emergency landing in Sarasota, has rescheduled the press conference for Wednesday morning.

Web Editor Susan R. Miller contributed to this report.


source: south florida business journal

link to the original post:
http://southflorida.bizjournals.com/southflorida/stories/2008/11/10/daily11.html

Fort Lauderdale Blog and Real Estate News
Rory Vanucchi
RoryVanucchi@gmail.com

www.LasOlasLifestyles.com
www.FortLauderdaleLiving.net
CHANGING WATER COLOR

Why There’s Blue And Brown Water In The Same Place

If you spend any time in the Intracoastal Waterway you’ll notice
huge changes in the water. Some days it’s gorgeous crystal clear blue water. Other days it’s murky. Still on others it looks like coffee. What’s happening?

The change in water color is caused by the
tides. On an incoming tide, clear ocean water streams through the inlets, flooding parts of the Intracoastal Waterway. On an outgoing tide, brown water from inland canals and the Everglades is sucked out the inlets.

The brown water isn’t appealing, but it’s
not dangerous. It’s brown because tanic acid is released from decaying vegetation. The shades of brown vary with rainfall. For several days after a major rain storm, darker canal water is released. This can vary the color of low tide Intracoastal Waterway water from light brown to coffee.

The blue water can vary in clarity depending on the
Gulf Stream. If the Gulf Stream is close to our area, the water can even clearer than usual.

The best places to enjoy clear water are near inlets. Clear water will begin pushing out the brown water from about three hours before high tide until high tide. The clear water will begin to recede after high tide. Residual clear water should remain in the area for a couple of hours following high tide.

Many times the meeting point of blue and brown water is quite pronounced. You will see
sharp “lines” form where the brown water meets the blue. You can see this in the photo below:


The "blue meets brown water line" is even more pronounced from the air.

See comparison photos of blue and brown water in the same area.

If you are flying out of Palm Beach International Airport, look at the Lake Worth/Palm Beach Inlet as you fly over. You will immediately know if the tide is going out. You will see a huge current of brown water getting sucked out to sea.

NOTE: Sometimes water managers release water from Lake Okeechobee through the Okeechobee Waterway and out the St. Lucie Inlet. Water from the lake can be heavy with pesticides and fertilizers. In the St. Lucie area, it’s best to avoid swimming during a Lake Okeechobee release.

original post: http://www.geocities.com/palmbeachboating/water_color.html


Fort Lauderdale Blog and Real Estate News
Rory Vanucchi
RoryVanucchi@gmail.com

http://www.lasolaslifestyles.com/
http://www.fortlauderdaleliving.net/

Citigroup includes South Florida in risk-prevention program

Citigroup will reach out to 500,000 borrowers with help to avoid foreclosure in markets experiencing especially tough times. Even borrowers who have not fallen behind are eligible for help in key locales, including South Florida.


mhatcher@MiamiHerald.com

Saying it will target borrowers in markets likely to face extreme economic distress and further declines in home prices, Citigroup, one of the nation's largest banks, will expand its foreclosure prevention efforts to include borrowers who are still current on mortgages, the company announced Tuesday.

Up to 500,000 Citi customers are expected to qualify for the new mortgage assistance program. The company estimates about 130,000 homeowners will receive help over the next six months, affecting $20 billion in mortgages. These include homeowners in South Florida.

Citi's plan will be extended to customers regardless of the type of loan they have, unlike other foreclosure prevention efforts that have sought to stem losses among borrowers with high-risk subprime, adjustable-rate, and negative amortization loans.

Last month, JP Morgan Chase said it was launching a new effort to help more than 300,000 customers avoid foreclosure on $70 billion worth of mortgages and would hold off on filing new foreclosures for 90 days. Citi is indefinitely suspending new and existing foreclosures while it attempts to contact eligible borrowers.

Loan modification plans will include a combination of interest-rate reductions, principal forgiveness or term extensions. The company said it also was working with investors to extend mortgage assistance to loans not owned but serviced by Citi. So far, the bank says it has averted foreclosure for 370,000 customers since the start of 2007.

Citi's loss mitigation program builds on renewed efforts within the lending industry to more aggressively reach out to at-risk customers amid mounting losses. There also has been increased pressure from congressional leaders resulting from the passage of a $700 billion financial rescue package. Last month, Citi reported a $2.8 billion loss for the third quarter. Reports published Monday said that Citi was likely interested in tapping rescue funds for the purchase of a regional bank.

Sanjiv Das, chief executive of CitiMortgage, said the bank was charting a new path by focusing on customers who are still current.

Rather than responding to the region's vast number of borrowers who owe more on loans than their homes are worth, Das said the bank would look at the broader economic indicators to target at-risk customers, particularly living in areas hit by job losses and falling home values that exceed the national average. South Florida made that list, Das said.

''This is in response to a lot of borrowers who are current with us, but are likely to default because of some significant change in their economic circumstances,'' Das said. ''Rather than having them go through the pain of missing a payment or missing several payments and getting into deep delinquency and foreclosure, why don't we reach out before? That way it doesn't damage their credit score. It's the same loan modification at the back end, so why wouldn't we offer it to them on the front end?'' Citi will open several new Borrower Relief Centers with additional staff. The company said its modification model will be patterned after efforts by the FDIC to restructure the loans of IndyMac customers after the bank failed in July.

The IndyMac plan uses a simplified formula that determines payment affordability as 40 percent of a borrower's income and can include a reduction of the interest rate and principal as well as an extension of the time period over which a loan must be repaid.

Das said some customers would see interest rates reduced to as low as 1 percent for periods up to two years, or enough time to see them through their difficulties.

Citi said eligible customers are those who live in the mortgaged property as their primary residence, work with the company in good faith, and have sufficient income for affordable mortgage payments.

Customers will be contacted directly by the lender, although they may visit http://www.mortgagehelp.citi.com/ for more information.


source: miami herald


Fort Lauderdale Blog and Real Estate News
Rory Vanucchi
RoryVanucchi@gmail.com

www.LasOlasLifestyles.com
www.FortLauderdaleLiving.net